VCG INSIGHTS · BRIEFING · OCTOBER 2026
By Bhavik Khatri, Founder & Managing Principal
The Rate Reset Arrived
Capital is still moving, toward shorter money and safer seats.
Data through October 22, 2026, unless noted.
September’s hike left the capital markets open, but it changed which lenders are winning the business. Long rates near 5% are pushing borrowers to floating money from banks and debt funds. Maturities are now driving most of the distress. And construction money is there at the right attachment point, but for most sponsors the cost of filling the stack is coming out of equity returns.
Three changes that matter
1. The yield curve is choosing the lender. The ten-year Treasury peaked at 5.31% on October 5 and has spent most of the month near 5%. SOFR has held near 3.88%.
Fixed-rate lenders price off the long end and floating lenders off SOFR, so with more than a point between them the curve is largely deciding who makes the loan. Balance-sheet lenders win the business, and the refinancing risk moves out to 2028. I’ll be looking at whether long rates settle below 5% after the Fed meets on October 28.
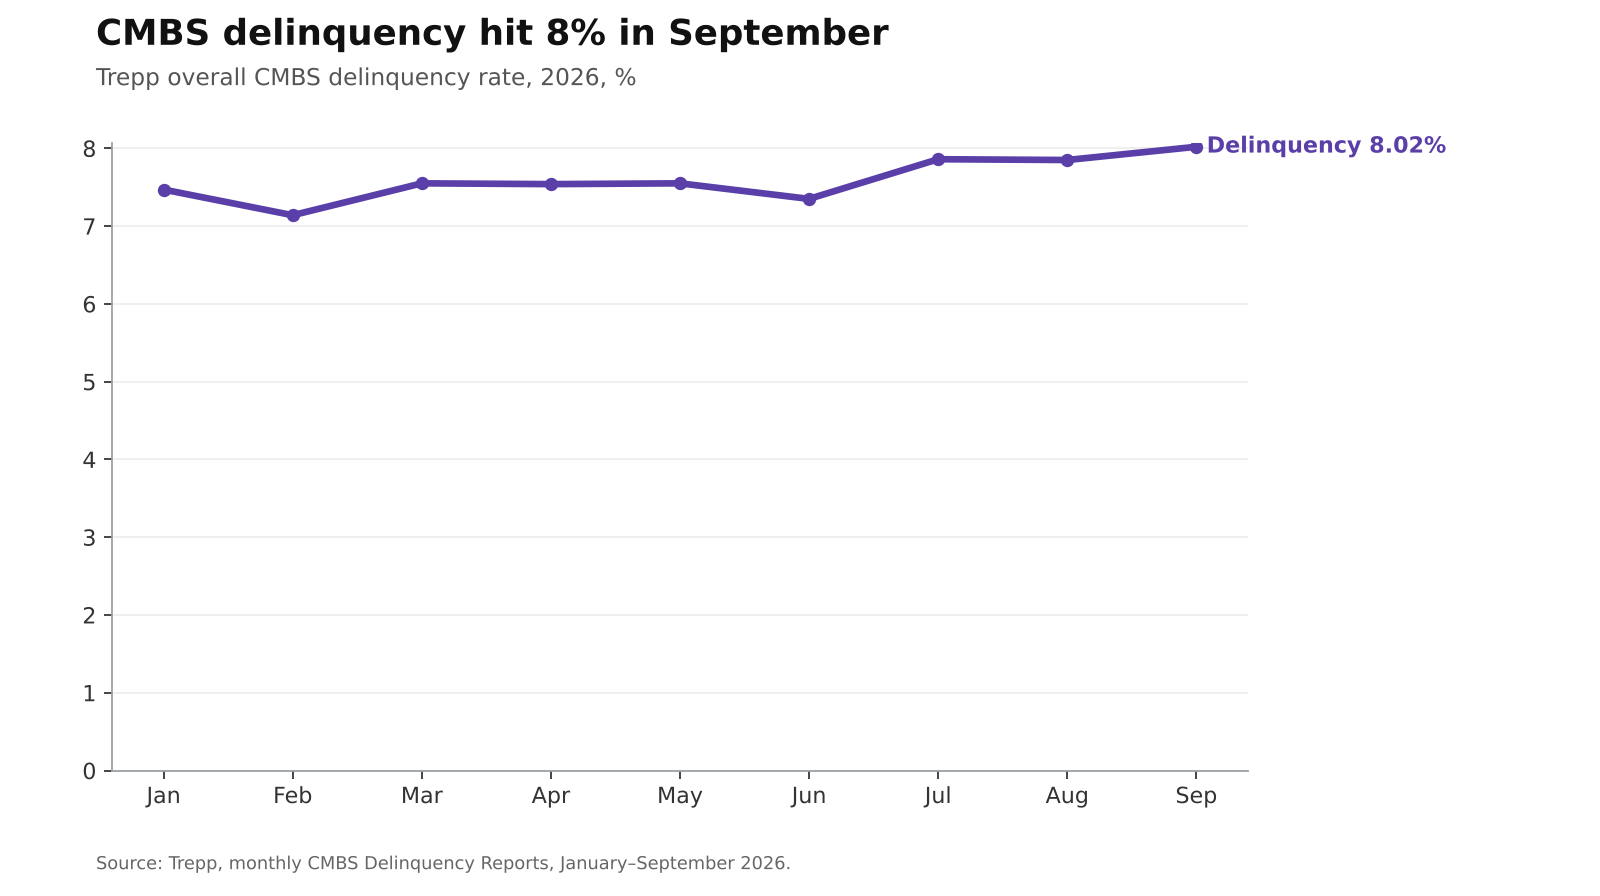
2. Maturity is driving distress. CMBS delinquency rose to 8.02% in September, and special servicing reached 11.49%, the highest since early 2013. Some loans moving to special servicing were still current. They just couldn’t refinance at maturity. Only about 58% of CMBS loans reaching final maturity in September paid off on time.
In many of these cases the property is performing; what’s missing is the layer between today’s smaller senior loan and the owner’s equity, which is pref and mezz. Nearly 39% of this year’s $76.6 billion of CMBS hard maturities fall in the fourth quarter, so the October special servicing report in mid-November should show whether the pattern is holding.
3. Construction capital is available. The question is where it attaches. Multifamily permits were about 1% above last year in September, but multifamily starts fell about 26%. Over the same weeks, JPMorgan led a $1.1 billion construction loan for an Extell tower, and it is reportedly in talks on a $3.8 billion loan for another.
A permitted project that can’t start can become a supply gap in 2028 or a sale today, and either way it usually needs new capital before a bank construction loan will close. October starts are due November 18.
Lender appetite
!Debt funds peaked in Q1. Banks are closing in.
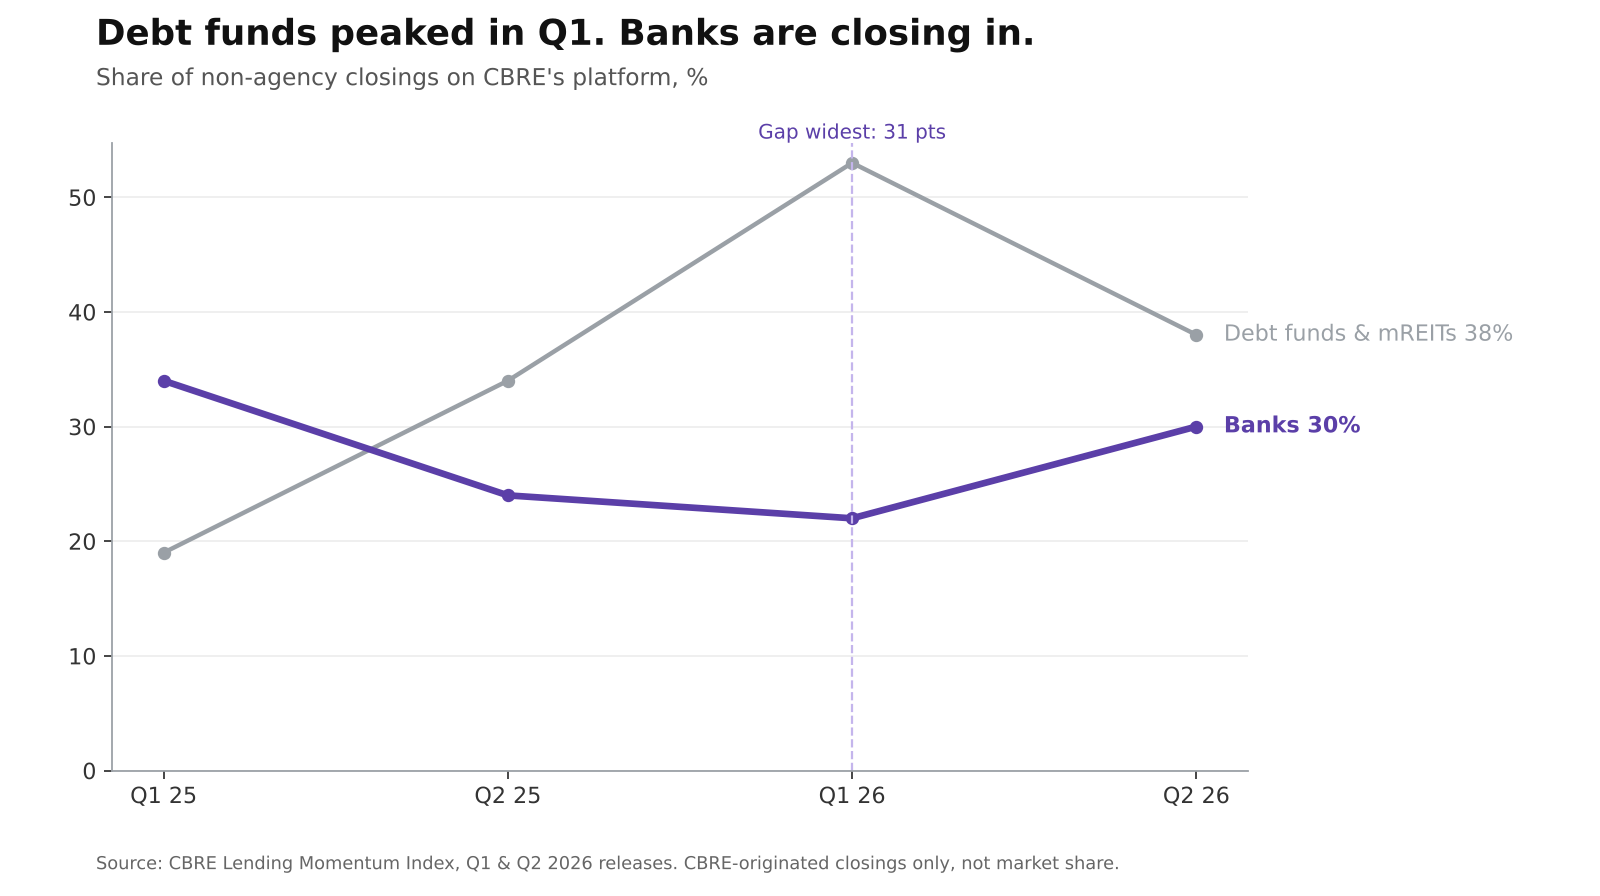
On CBRE’s platform, debt funds and mortgage REITs closed 53% of non-agency loans in Q1 2026 and 38% in Q2. Banks rose from 22% to 30%. FDIC data show bank loans to nonbank lenders up 22.4% year over year in Q2, against 4.1% for bank commercial property loans. Banks are growing loans to other lenders more than five times as fast as loans on buildings, though not all of that lending is real estate.
If fund spreads on transitional deals widen more than bank senior spreads this quarter, I’d read it as banks repricing the lines behind the funds. CBRE’s Q3 lender mix is due in early November.
The data
!CMBS delinquency hit 8% in September
Calendar
Two threads carry into next month: how fund spreads move against bank spreads, and whether the conditions in Themes No. 1 start to shift. I’ll come back to both as the data comes in.
Sources and methodology
- Sourcing note: we cite the organization that produced each figure. Where its own release isn’t publicly accessible, we name the outlet we read it in.
- Rates:
- Federal Reserve, FOMC statement (Sept 16, 2026).
- Treasury yields: Federal Reserve H.15 via FRED (DGS10, DGS2). The 10-year was 5.31% on Oct 5 and 5.13% on Oct 21; the 2-year was 4.81% on Oct 21.
- SOFR: Federal Reserve Bank of New York (3.88% on Oct 21).
- CMBS performance:
- Trepp, CMBS Delinquency Report, September 2026. Sector rates are as published by Yield PRO and Multifamily Dive.
- Special servicing: Trepp data, as published in CREFC’s Update on CMBS Loan Performance, September 2026.
- Maturity payoff: Commercial Real Estate Direct, Oct 21, 2026, using Trepp data.
- Hard maturities: Trepp, Spring 2026 Quarterly Data Review (May 2026).
- CMBS issuance: Trepp, TreppWire (October 2026).
- Lender mix: CBRE, Lending Momentum Index press releases, Q1 (May 2026) and Q2 (Aug 3, 2026). These are CBRE-originated closings only, not market shares.
- Bank credit: FDIC, Quarterly Banking Profile, Q2 2026, Table II-A and narrative.
- Prices:
- Green Street, Commercial Property Price Index release (Oct 6, 2026).
- MSCI, RCA CPPI for August 2026, as summarized by SVN (Sept 25, 2026). MSCI’s full report requires registration.
- Construction: U.S. Census Bureau and HUD, New Residential Construction, September 2026 (Oct 20; preliminary).
- Construction loans:
- Upper West Side: Bloomberg (Sept 24, 2026). The $3.8B loan was reported as in talks.
- Times Square tower financing: The Real Deal (Sept 25, 2026).